Ep 237 | Art Berman
A World-Changing Event: We’re Not Going Back to January 2026
Description
Four months after the Iran war first rattled global energy markets, the global system has proven surprisingly adaptable, even as prices continue to rise and product shortages become more common. But as those buffers run dry and diesel prices climb to the equivalent of over $200 a barrel, the slack in our system is starting to disappear. How much longer can our hyper-connected economic system stagger along, and where is it already breaking?
In this episode, Nate welcomes back petroleum geologist Art Berman for a follow-up to their May conversation, to take stock of what’s changed since the war upended Middle East energy flows. Art explains why the adaptations that have kept prices from spiraling have unaccounted-for costs for the larger system, and why 5 to 20 percent of shut-in production may never return to prior levels, even once wells are reopened. The conversation traces the parallels between this moment and the 1970s and 1980s oil shocks, but also the key differences that will create a bigger (potentially insurmountable) barrier to recovery this time. Ultimately, Nate and Art consider whether we are witnessing the rise of a fragmenting, multipolar world of resource nationalism that will replace the postwar security architecture, which has underwritten cheap oil and globalization for decades.
How are underlying refinery risks intensifying an already precarious situation? How are global powers positioning themselves amid this pivotal point for geopolitical relationships? And even if the multiple global conflicts were to stabilize today, what are the locked-in repercussions for global energy supplies, and how will they ripple out to affect everything around us?
About Art Berman
Art Berman is a petroleum geologist with over 40 years of oil and gas industry experience. He is an expert on U.S. shale plays and is currently consulting for several E&P companies and capital groups in the energy sector.
Show Notes & Links to Learn More
Download transcriptGuest:
- Art Berman: Independent petroleum geologist and energy consultant, Works
- Previous The Great Simplification appearances
- Art’s presentation/figures for this conversation
Grab-and-Go Resources:
New? Start here:
- The Superorganism Explained in 7 Minutes (Frankly #97)
- Energy Blindness (Frankly #3)
- The Great Simplification (32-minute film)
From the Archive:
- Ep 220: A World On the Precipice: The Last Oil Tanker From the Strait of Hormuz has Arrived – Now What?
- Ep 235: The Escalation Trap: Is America’s Strategy in Iran Backfiring?
- Frankly #61: The Strait of Hormuz and the Spice
Episode Foundations:
- Art’s essay The Iran War Phase Shift, Art’s presentation/figures for this conversation
- IEA Oil Market Report, September 2026
- York and Bell, Energy transitions or additions?
Next Steps:
- Weekly data briefing: This Week in Petroleum
- How-to: Gas Mileage Tips
Resources by Timestamp:
03:09 – 2026 Iran war (Latest developments)
03:43 – Global energy supply growth rate falling since the late 1960s
04:25 – ~10 million barrels a day of Gulf oil supply suddenly lost
05:05 – Global population growth rate peaking in the 1960s
05:30 – *Fossil fuels at 86% of global energy in 2025, Oil the largest single source
06:08 – Energy costs of maintaining complexity at the scale of 8.2 billion people
07:19 – 2026 Iran war fuel crisis in Asia
07:36 – Energy blindness, Technology dependent on energy and materials
08:49 – U.S. record energy production from oil, natural gas and coal
09:01 – Import-dependent regions hit hardest: Asia, Africa, Europe
09:45 – Art’s May 2026 presentation, The Hormuz Crisis: A Systems Perspective (The Great Simplification Ep 220)
09:58 – 2026 Strait of Hormuz crisis, ~20 million barrels a day through the Strait of Hormuz
10:35 – Supply-loss cushions: Hormuz bypass pipelines, Emergency oil stock releases
10:40 – *China’s seaborne crude imports down 3.6 million barrels a day from February to April
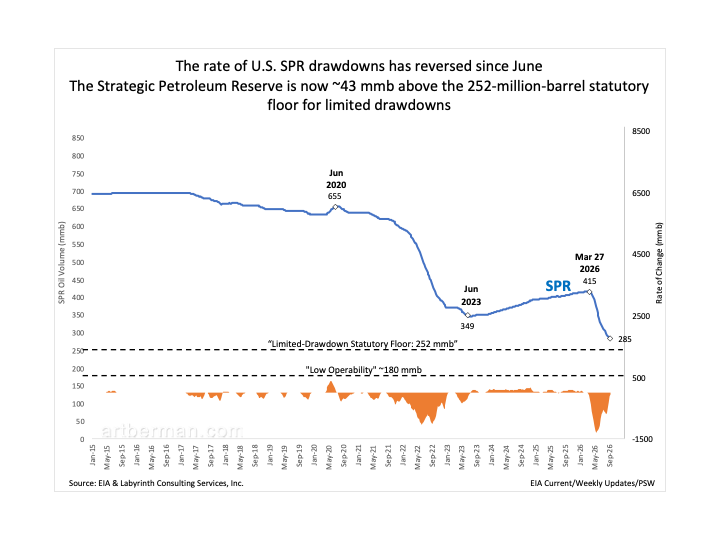
11:16 – SPR Drawdown Rate In-video insert
11:23 – U.S. Strategic Petroleum Reserve at its lowest level since 1982, Risk of damaging SPR salt caverns at low levels
13:05 – *SPR drawdowns peaking in May and slowing since
13:57 – Strategic Petroleum Reserve’s purpose as an emergency buffer
14:30 – Global oil inventories down 507 million barrels since February, Demand destruction
15:13 – International Energy Agency’s Oil Market Report
15:36 – Resilience of the Economic Superorganism (Frankly #97)
16:01 – 2026 East–West pipeline attack, Drones from Iraq shutting a pipeline moving 4–5 million barrels a day
16:39 – Narrow- vs. wide-boundary perspectives
16:49 – Oil buffers: China’s strategic petroleum reserve, Oil stored on tankers at sea
16:58 – Middle East oil reserves as civilization’s buffer
17:54 – Unipolarity (U.S. military superiority)
18:00 – The Carbon Pulse, Possible future shapes of the Carbon Pulse, Future growth scenarios
18:06 – Peak oil driven by above-ground factors vs. Geological depletion
18:24 – Oil flows vs. stocks
18:50 – *Based on the May IEA report: Gulf output 14.4 mb/d below pre-war, updated numbers in the September IEA report, with more than 10 mb/d still shut in
19:38 – 1970s energy crisis comparable as a share of global supply
20:19 – 1979 oil crisis, Iran–Iraq War, Iranian Revolution (founding of the Islamic Republic)
20:31 – *World oil production not regaining its 1979 level until late 1996
21:15 – 1980s oil glut from a price-driven exploration boom
21:38 – Dissolution of the Soviet Union, Caspian oil opened after the Soviet collapse
21:47 – Proved oil reserves
22:01 – World population nearly doubling since 1980
22:51 – Investor retreat from fossil fuels: Fossil fuel divestment, Environmental, social and governance (ESG) investing
23:20 – Peak oil demand
23:39 – Underinvestment in deepwater exploration and new oil refineries
25:25 – Oil demand growth slowing from ~2 to ~1 million barrels a day a year
25:44 – Frankly #124 on the biophysical gauntlet of oil production
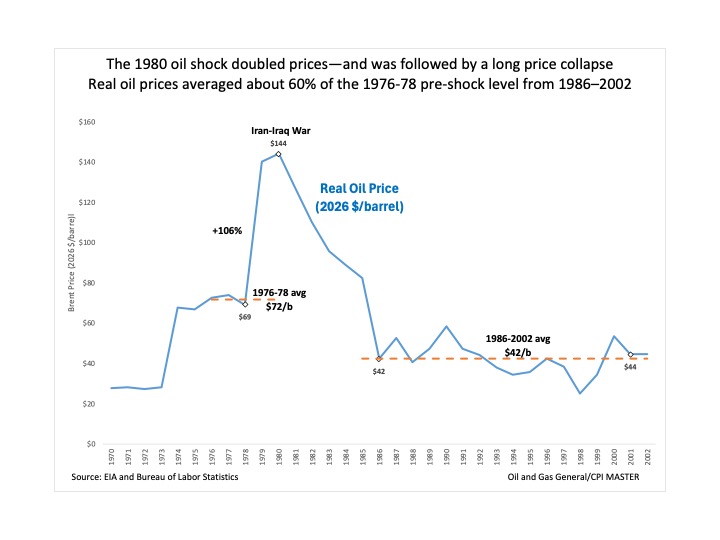
26:20 – 1980 Oil Shock Prices In-video insert
26:45 – Cold War energy order vs. Today’s fragmented energy system
27:16 – OPEC under strain after the UAE’s exit, BRICS, Power of Siberia 2 and China–Russia energy and currency ties
27:28 – Russo-Ukrainian War
27:53 – Hormuz shuttle tankers and ship-to-ship transfers
28:22 – *, Chris Wright claiming record Persian Gulf oil flows of ~18 million barrels in a day
28:41 – East–West Crude Oil Pipeline to the Red Sea, ~5 million barrels a day of crude exports via Yanbu
29:09 – Houthis, Rerouting Yanbu crude through the Suez Canal
30:09 – Orwellian
30:17 – Donald Trump saying the war will end after the midterms and gas prices will fall, 2026 U.S. midterm elections
30:33 – Gas prices crashing 61% in six months in the Great Recession
30:39 – Islamabad Memorandum (U.S.–Iran memorandum of understanding)
31:18 – U.S. military bases in the Middle East
32:13 – 1980s developing-world debt crisis
32:46 – Months of mine clearance and shipping backlog before Hormuz normalizes (Art’s May estimate of ~2 months even if the conflict ends)
33:09 – War-risk insurance for tankers
33:31 – Naval mines in the Strait of Hormuz, Islamic Revolutionary Guard Corps, Tanker El Gaia struck near Hormuz
34:22 – Months to restart shut-in Middle East oil wells
35:44 – Reservoir rock: Porosity, Permeability, Tortuosity
36:39 – Crack spreads (crude vs. refined product prices)
36:54 – U.S. diesel above $200 a barrel
37:41 – Products from a barrel of crude: Gasoline, Diesel, Jet fuel, Kerosene, Petrochemical feedstocks
37:49 – Refining system stretched to its limits
38:11 – Dangote refinery
38:36 – Electric vehicles still need oil: Plastics in electric cars, Bitumen for asphalt roads
40:16 – 1970s responses: Nuclear power build-out, Fuel economy standards, North Sea oil
40:32 – Today’s options: Faster electrification, Return to coal, Resource nationalism
40:41 – China’s expected coal power expansion in 2027
41:11 – Energy additions rather than energy transitions (Global primary energy use by source)
41:43 – *Traditional biomass use roughly double its 1800 level
41:59 – Coal use at record highs globally, Falling U.S. coal use
43:29 – Early 1980s recession after the oil shocks
43:59 – U.S. shale’s response to the oil shock
44:37 – Art’s long-running shale skepticism: Beginning of the End for the Permian (The Great Simplification Ep 101)
45:08 – 10-year Treasury yields near 5%, U.S. national debt topping $40 trillion
45:23 – Permian tight oil driving U.S. shale growth as other plays fade
45:38 – Depleted U.S. missile interceptor stockpiles
46:35 – Narrow-boundary optimism: AI investment boom, Stock markets at record highs
46:54 – Leonardo DiCaprio, Titanic, Titanic’s musicians playing on as the ship sank
47:09 – Technological utopianism (technology as mythology)
48:09 – Cornucopianism
48:19 – Green Revolution, Thomas Malthus
48:40 – Synthetic fertilizers (Haber process) and mechanized agriculture
49:06 – Externalities: Agricultural fertilizer pollution, Groundwater depletion (falling water tables), Soil salinization
49:31 – Diminishing returns on technology
50:08 – Qatar’s LNG exports, Roughly a third of global urea exports and 20% of ammonia exports via Hormuz
50:23 – *FAO warning of larger food supply shocks in 2027 and beyond, Global fertilizer shortage at planting time
50:41 – Food system risks: European drought, Super El Niño (very strong El Niño forecast into 2027), Ukraine’s food exports at 40% of capacity under Black Sea blockade
51:13 – Global natural gas squeeze
51:22 – Energy protests: Syria fuel price protests, Bangladesh power-cut protests
52:05 – *European gas near $27 per million BTUs vs. Under $3 at Henry Hub
52:18 – Volkswagen job cuts and repurposed German plants
52:22 – Europe’s lost Russian gas, Deindustrialization of Europe
52:47 – Europe swapping Russian gas for U.S. and Qatari LNG
53:23 – Liquefied natural gas cooled to about −162 °C, [Correction: LNG is routinely transferred ship-to-ship, and one operator has completed more than 3,000 transfers]
53:54 – Importers storing oil and gas closer to home, Game theory
54:33 – Jeff Currie on state capitalism (The Great Simplification appearance)
55:11 – Trump administration’s government stakes in companies, U.S. stake in a Venezuelan oil venture
55:47 – Venezuelan heavy crude and U.S. gasoline
56:25 – U.S. light oil suited to gasoline, not diesel: America Has Plenty of Oil—Just Not the Right Kind (The Devil Is in the Diesel)
57:13 – ~4 million barrels a day of U.S. crude imports from Canada, U.S.–Canada trade war
57:49 – Upgrading heavy crude: Fluid catalytic cracking, Hydrocracking
58:28 – Robert Pape (The Great Simplification appearance)
58:36 – Petrodollar and U.S.–Saudi defense agreements
58:56 – Frankly #61 on the security architecture behind ‘the spice’
59:10 – U.S. Navy as guarantor of free maritime trade, Dollar as world reserve currency
1:00:24 – Gulf states seeking other security partners
1:00:58 – Henry Kissinger, 1974 U.S.–Saudi petrodollar deal
1:01:42 – Eurodollar system, Money creation out of nothing by bank lending
1:03:48 – Competition for critical resources
1:05:02 – China’s dominance in resource processing and refining, Silver export controls
1:05:43 – Trump’s order to increase American mineral production
1:06:13 – Oil and the World Wars: Allied oil advantage in World War I, Germany’s fuel shortage in World War II, Japan, the U.S. oil embargo and Pearl Harbor
1:07:14 – Refilling strategic petroleum reserves
1:08:28 – Supply recovery projections: IEA, EIA
1:09:05 – Optimism bias in agency forecasts (Shale Reality Check)
1:10:19 – *EIA outlook of ~112 million barrels a day of world production by late 2027
1:11:22 – Hormuz vessel traffic counts
1:11:51 – Airline cuts in the 2026 Iran war fuel crisis
1:12:01 – China’s crude imports down 38%, to ~8.2 million barrels a day